Operations · Notes
What should an independent insurance agency owner review every month?
Short answerReview booked financial results, Book movement, retention, coming renewals, and genuine new business for a named period. Then identify the items an owner or manager needs to examine. No single KPI can provide the whole operating picture.
John RanieriFounder & Product Lead, Keelridge SoftwareSeptember 10, 2026 · 5 min read
Which questions belong in the monthly review?
Start with questions, not a wall of metrics. The purpose of the review is to explain what changed, separate the causes, and identify the small number of items that deserve follow-up.
| Owner question | Primary evidence | What to review |
|---|---|---|
| Did the agency make money? | Closed accounting period and approved budget | Booked revenue, operating expenses, profit, EBITDA, and variance from plan |
| Did the book of business grow? | Dated AMS book snapshots | Opening and closing premium, customers gained or lost, transfers, and change on retained customers |
| Did we keep the customers we started with? | One opening customer cohort followed to the ending date | Client, premium and commission retention on the same opening cohort, alongside the distinct renewal rate |
| What is coming due? | Current AMS policies and renewal dates | Renewal load, material premium changes, and the accounts requiring early review |
| Is new business producing real growth? | Human-owned opportunity records and AMS arrivals | Received, bound, and lost opportunities compared with gained customers, acquired arrivals, and genuine cross-sell in the Book |
| Do the operating and accounting stories agree? | Trailing-twelve-month booked GL P&C commission and Book earning power over the same months | Recorded, annualized, and modeled earning power; timing and unexplained; and growth from the window average to today |
Why does a complete review need more than one reporting basis?
An agency management system holds the operational record for customers, policies, carriers, premium, renewal dates, and expected commission. Some AMS platforms also hold accounting records. Even within one platform, an in-force Book snapshot, posted accounting activity, the approved budget, and cash commitments describe different parts of the business.
An accounting report shows booked revenue, expenses, and profit. Understanding which customers stayed, which accounts arrived or left, what changed on retained customers, and who owns an upcoming renewal requires the corresponding Book and responsibility evidence.
A reliable owner review therefore assembles these reporting bases around management questions, whether they come from one platform or several. The source and period should stay visible wherever their numbers are used.
How can an owner build a useful first version manually?
A spreadsheet can work as a starting point if the agency uses the same process every month. The discipline matters more than the design.
- Name the period. Decide which completed accounting month and which dated AMS snapshot the review represents. Do not quietly mix a current Book with an older P&L.
- Keep the original exports. Save the source files used for the review so a surprising figure can be traced instead of reconstructed from memory.
- Freeze the definitions. Decide what counts as a customer, retained business, genuine new business, a transfer, and a material premium change before comparing months.
- Bridge the Book. Separate customers who left, customers who arrived, transfers or acquisitions, and premium change among customers who stayed.
- Compare rather than force. Compare trailing-twelve-month booked P&C commission with average Book earning power over those same months. Show growth from that average to today separately and leave timing and unexplained visible without assigning it a cause the records do not prove. The Book-to-GL Note walks through that basis.
- Assign the follow-up. End with the renewals, exceptions, or questions that belong to a specific owner, manager, or account manager.
Which time periods should an agency compare?
Use the completed month to spot recent movement, year to date to understand progress through the current fiscal year, and a comparable prior-year period to separate seasonality from a real change. A trailing twelve-month view can help with run-rates, but it should not be labeled as year to date.
The comparisons need the same definitions on both sides. If one period counts acquired customers as organic arrivals or uses a different commission assumption, the apparent trend may be a classification change rather than operating performance.
How should the review turn numbers into work?
An owner should not leave with twenty charts to remember. The review should end with a short set of explicit questions: which financial variance needs an explanation, which Book movement needs classification, which renewal needs early attention, and who owns each follow-up.
Owners, department managers, and account managers do not need identical screens. The owner needs agency-wide economics and movement. A manager needs team coverage and exceptions. An account manager needs their own renewals, premium changes, and Book context without agency-wide financial exposure.
Those views can use the same governed records while revealing only what each role needs for its job.
What does Keelridge remove from the process?
The calculations are not usually the hardest part. Finding the inputs, repairing changing report formats, keeping customer identity consistent, applying the same definitions, and rebuilding the comparisons every month are the recurring work.
During implementation, Keelridge maps the supported reports, agency facts, definitions, roles, and Book assignments. For the recurring review, the agency supplies the regular AMS Book and accounting files; each file is staged and validated before it updates the governed views. Keelridge then fills the monthly, year-to-date, and year-over-year review without asking the owner to collect separate account-manager reports or retype every figure into a calculator.
The AMS and accounting system remain authoritative. Keelridge organizes the review around them, preserves the differences between them, and carries the result into the appropriate owner, manager, and account-team views.
What the owner sees first
One operating view, with the period and evidence attached.
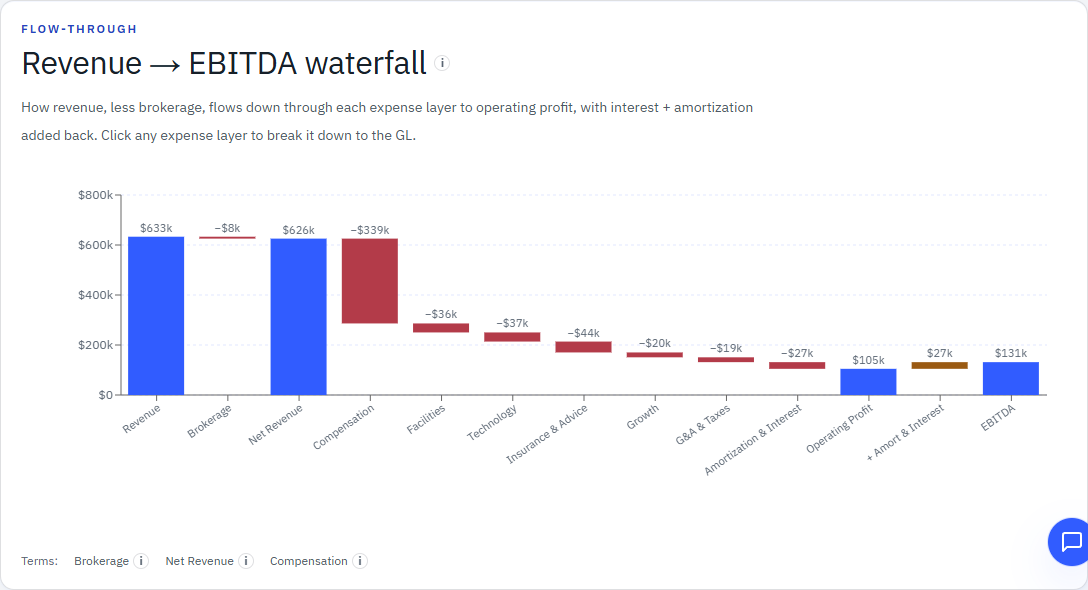 Owner viewOpen this page in the live demo →
Fictional Keelridge Demo Agency. The owner starts with financial and Book movement, then opens the supporting view instead of treating the summary as an unexplained score.
How movement stays explainable
Growth is separated into what arrived, left, transferred, and changed.
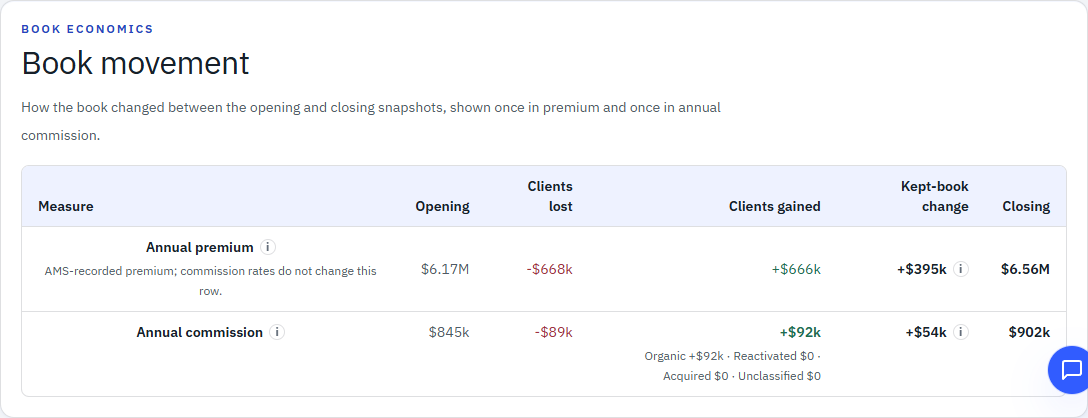 Owner viewOpen this page in the live demo →
Fictional Keelridge Demo Agency. The Book bridge prevents rate and exposure changes on retained customers from being mistaken for new business.
Start with the six questions, not six new dashboards
Use one completed accounting period and one dated AMS Book, answer the six owner questions on a consistent basis, and write down what still needs explanation. If preparing those answers depends on several people, repeated exports, or a workbook only one person understands, that preparation process—not another KPI—is the problem to solve.