Financials · Notes
Did my insurance agency acquisition pay for itself?
Short answerAsk whether the purchased customers are still with the agency, then ask what the deal has earned back. The first answer comes from dated AMS Book snapshots. The second compares the price with acquired-book commission after payouts and financing costs. A single premium total cannot answer both.
John RanieriFounder & Product Lead, Keelridge SoftwareSeptember 12, 2026 · 6 min read
Why doesn't the purchase price answer whether the deal worked?
A purchase price records what the buyer agreed to pay. It does not show how much of the purchased customer base remained, what that Book produces now, or how financing and accounting charges affect the agency after closing.
That is why post-close review matters. Insurance Journal's 2026 discussion of agency acquisition economics argues that amortization, interest, tax allocation, and owner distributions can make actual results diverge from the original projection. Keelridge does not replace a full deal model, tax analysis, or valuation. It gives the owner a recurring operating view of the parts supported by the agency's Book, deal facts, and mapped ledger accounts.
How can an owner tell whether the acquired Book is still here?
Give each acquired Book a stable identity, record when it became the agency's responsibility, and follow its customer and premium history across dated AMS snapshots. Customer count is the clearest survival signal because premium can rise with rate, exposure, or coverage even while relationships leave.
The first months need special care. A purchased Book may appear gradually as policies renew and are rebooked onto the buyer's AMS. Those accounts are the purchased Book moving onto the system—not organic new business. Customers who leave count as losses from day one, while genuinely new customers sold under the acquired Book's codes remain visible as new sales. A customer whose same policy comes back within 14 months is treated as kept, not lost.
| Movement | Classification | Why it matters |
|---|---|---|
| Starting position | Customers already visible when tracking begins | The first supported view of the purchased asset |
| Moved in | Purchased customers rebooked within 12 months of the service date | Part of the acquisition arriving—not organic growth |
| New sales | Genuinely new customers written after the Book became yours | Growth created after closing |
| Returning | Customers who left and came back on a different policy, or after more than 14 months | Shown on their own; their departure still counts as lost, and their return is not counted as a new sale |
| Lost | Customers from the acquired Book who left the agency | Attrition against what the agency purchased |
| Kept book | Premium change on customers held at both dates | Rate, exposure and coverage movement on customers who stayed |
| Now | The customers measured at the latest snapshot | The current customer base carried by the acquired Book; the steps above should reach it |
What does 'paid for itself' mean?
It needs an explicit definition. Keelridge's deal-payback estimate credits the commission on every policy term under the acquired Book's codes that started after the Book became the agency's. Each term counts once, in the month it starts, which is when the ledger books it. It also credits what the Book paid after closing on policies written before it (a policy still in force at closing, or a premium audit), in the month the Book became the agency's. It subtracts the 1099 producer payouts on those terms and each month's note interest, then compares the running total with the purchase price. The purchase price includes the down payment plus note principal; principal payments are not subtracted again because they repay that same price.
This is an operating estimate, not cash-basis accounting. Where the agency's AMS records less commission than its ledger, the estimate is conservative; that assumption is stated beside the figure. A Book bought before the agency's first snapshot on file shows a floor, not a full history. The estimate does not invent overhead, tax, or integration costs that the available records cannot attribute to one Book.
The result should therefore be read as estimated purchase-price recovery from attributable Book earnings. It is useful for comparing the deal with its own history and assumptions. It is not a certified investment return or a replacement for the agency's accountant, lender, or transaction adviser.
Why should accounting net and cash net stay separate?
Amortization is an accounting charge; principal repayment is a cash outflow. Combining them into one unlabeled net number makes the deal look more or less burdensome depending on which basis happened to be used.
| View | A useful calculation | What it answers |
|---|---|---|
| Current earning power | Annual in-force acquired-book commission | What active policies carrying the acquired Book's confirmed codes support now |
| Net to agency, last 12 months | Commission booked over the last 12 ledger months − 1099 payouts on those terms − amortization − interest, all over the same 12 months | What the Book leaves after mapped income-statement charges; amortization is non-cash |
| Cash after note payments, next 12 months | Commission booked over the last 12 months − payouts − note payments (principal and interest) due in the next 12 months; assumes the next 12 months book what the last 12 did | Whether current attributable earning power covers annual debt service |
| Deal payback | Cumulative booked commission − payouts − interest, compared with purchase price | How much of the agreed price the Book has approximately earned back |
Which records are needed for a defensible monthly review?
The minimum useful package is a sequence of dated AMS Book snapshots, a confirmed acquisition identity or producer-code map, the date the Book became the agency's responsibility, and the agreed purchase price. Commission, seller or producer payouts, note terms, and the mapped amortization and interest accounts make the economics more complete.
Missing evidence should remain visible. If the acquisition date is unknown, the observed trend is only the history on file. If an accounting account or statement period is missing, the related charge is unknown—not zero. If an executive code might represent both acquired business and an active producer payout, the owner needs to confirm the treatment before relying on the result.
- AMS Book snapshots. Customer, policy, premium, commission, and the stable codes that identify each acquired Book.
- Acquisition facts. Close or service date, purchase price, down payment, note principal, rate, and term.
- Accounting mappings. The GL accounts that contain amortization and note interest for each deal.
- Payout treatment. Any seller, producer, or 1099 share that remains attached to the acquired policies.
- Human confirmation. Owner approval of the codes, dates, terms, and exceptions that source reports cannot infer safely.
What does Keelridge automate after setup?
A one-time acquisition model becomes stale unless someone updates the Book, refreshes the ledger period, maintains the code map, and rebuilds the same comparisons. Keelridge carries those confirmed rules into the recurring agency review.
When the agency supplies its regular AMS Book and income-statement files, Keelridge stages and validates the new period, refreshes current acquired-book earning power and mapped charges, extends the per-Book retention history, and updates the payback estimate. The owner can see the agency-wide roll-up, open one acquisition, and trace the figure back to its source and definition without rebuilding a separate workbook each month.
The product does not decide whether to buy an agency, declare that a transaction was good, or replace legal, tax, accounting, or valuation advice. It keeps the post-close operating evidence current enough for the owner and advisers to ask better questions.
What this looks like in the owner demo
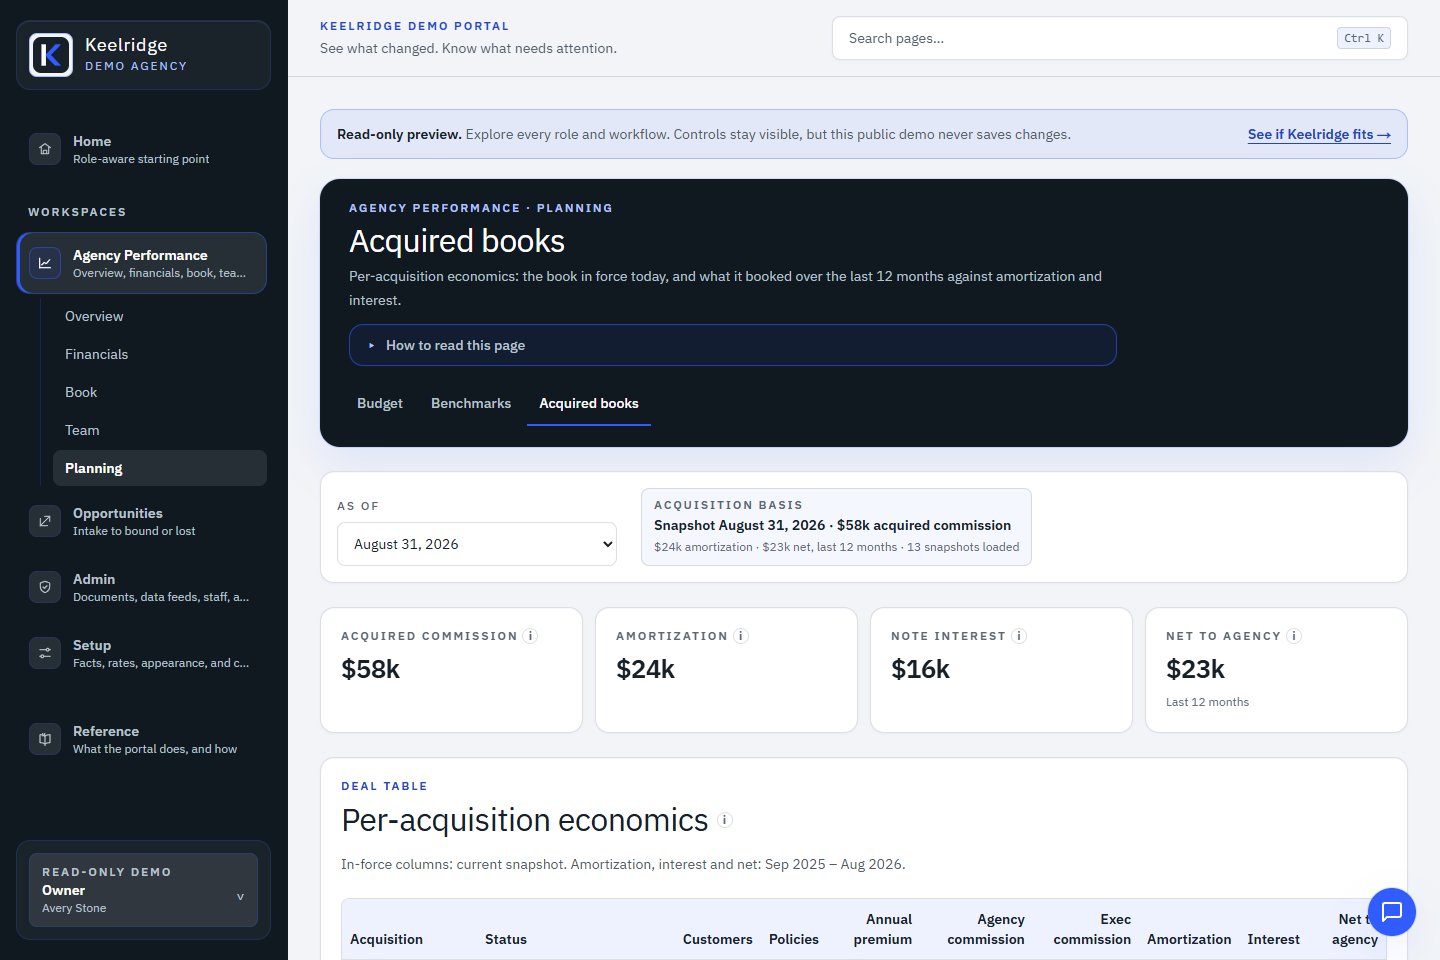
Current Book economics and deal charges stay on their own bases.
 Owner viewOpen this page in the live demo →
Fictional Keelridge Demo Agency. Each acquired Book's in-force size sits beside what it booked over the last 12 months, less amortization and interest, with per-acquisition detail below.
Review the asset and the financing as two connected stories
First ask whether the purchased customer relationships remain, using customer movement across dated Book snapshots. Then ask what the deal has earned back, with the purchase price, attributable commission, payouts, interest, accounting charges, and cash debt service kept on clearly labeled bases. That is more useful than one acquisition ROI percentage whose inputs and period cannot be reconstructed.
Sources used for the industry context
- Insurance Journal — Why Post-Close Economics Determine Acquisition SuccessIndustry discussion of why amortization, interest, tax allocation, and owner distributions can cause post-close results to diverge from an acquisition projection.
- Insurance Journal — 8 Things to Consider When Buying or Selling an Insurance AgencyLegal and transaction context on customer attrition, renewal-contingent purchase terms, earn-outs, and post-close risk in agency transactions.
- Big ‘I’ and Reagan Consulting — Best Practices Foundations: GrowthIndustry methodology distinguishing acquisition and divestiture activity from conventional organic growth while preserving retention and new business as separate drivers.